Aristocrat Just Walked Away From a $3.9 Billion Bid for Playtech. The Fallout Tells You Where the Power Sits.
The biggest acquisition in online gambling history didn’t fail because of price. Aristocrat offered roughly $3.9 billion for Playtech, a figure that valued the company at a significant premium over its trading price. The board recommended it. Shareholders were briefed. And then the whole thing collapsed, not because the money wasn’t there, but because the two sides couldn’t agree on what Playtech actually was. That distinction matters more than the dollar figure, because it tells you something important about how the companies supplying your casino lobby think about the online market versus the land-based one.
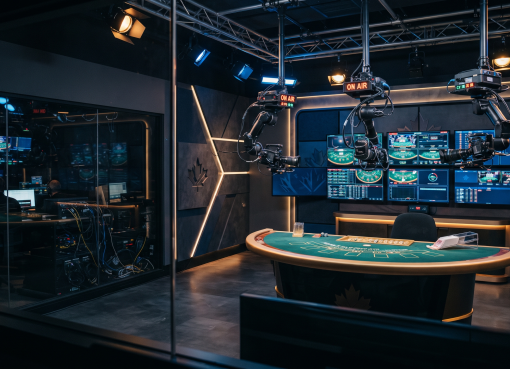
Aristocrat is a land-based gaming powerhouse. Slot cabinets in every major casino floor from Las Vegas to Macau, a portfolio of legacy titles that print money in physical venues. Playtech is the opposite animal: a digital-first supplier with live dealer studios, iLottery contracts, and a platform that powers online casinos across regulated markets. Aristocrat wanted Playtech’s online infrastructure. What it got instead was a lesson in how differently these two worlds value the same assets.
For Canadian players, neither company’s name appears on the login screen. But both sit behind the games and platforms you use every session. When a deal this size falls apart, it reshapes the competitive landscape that determines which games reach your lobby, how live casino tables are staffed, and which operators can afford to offer what.
What Playtech Actually Is to Canadian Players
Playtech doesn’t operate casinos directly. It builds the infrastructure that operators run on. If you’ve played at a casino powered by Playtech’s IMS platform, you’ve interacted with their technology without ever seeing the brand. Their live dealer product competes directly with Evolution in several regulated markets. Their game library includes Age of the Gods, Buffalo Blitz, and a catalogue of branded titles that show up in Canadian-facing lobbies regularly.
More importantly, Playtech holds iLottery contracts with several North American jurisdictions. That side of the business, the boring-sounding lottery technology arm, generates predictable, regulated revenue that doesn’t depend on player acquisition costs or bonus wars. It’s the part of Playtech that made Aristocrat’s board say yes in the first place.
The company also sold its financial trading division (Finalto) in a separate process, which I covered when it happened. That sale was Playtech stripping itself down to pure gambling technology. By the time Aristocrat came knocking, Playtech was a cleaner, more focused target than it had been in years.
What Actually Happened, and What the Timeline Reveals
Aristocrat’s initial approach valued Playtech at 680 pence per share, roughly $3.9 billion CAD at prevailing exchange rates. The Playtech board recommended the offer. Regulatory approvals were being sought across multiple jurisdictions. The timeline stretched across months, and that’s where the cracks started.
During the extended due diligence period, a rival bidder, the Hong Kong-based TTB Partners consortium, entered with a competing offer. Aristocrat didn’t engage in a bidding war. Instead, it walked. The official statement cited regulatory complexity and the extended timeline, but the subtext was clearer: Aristocrat decided the online gambling infrastructure it was buying wasn’t worth a protracted fight when its core land-based business was already generating strong returns.
What the public statements didn’t say is that Aristocrat’s own digital division, Pixel United, was already underperforming expectations. Buying Playtech would have meant absorbing a massive online operation while its existing digital strategy was still finding its footing. The deal didn’t collapse because of one problem. It collapsed because the accumulation of complications made the risk profile look different at month six than it did at month one.
The Mechanism Behind the Collapse
Land-based gaming companies have been trying to buy their way into online for a decade. The logic is straightforward: physical casino revenue is mature, online is growing, acquire the technology rather than build it. But the execution is brutal. The two business models run on fundamentally different economics.
A land-based slot cabinet generates revenue from a fixed install base. The machine sits on a casino floor, players walk up to it, and the operator pays a lease or revenue share. Player acquisition cost is essentially zero because the casino’s location does the work. Online is the opposite. Every player must be acquired through marketing spend, retained through bonuses and loyalty mechanics, and served through technology infrastructure that requires constant investment. The margins look similar on a spreadsheet but the cost structures are entirely different animals.
Aristocrat’s withdrawal suggests its leadership concluded that Playtech’s online revenue, while growing, carried acquisition and retention costs that made the $3.9 billion price tag harder to justify than the initial modelling suggested. The competing bid from TTB Partners didn’t help, but it wasn’t the cause. It was the catalyst that forced a decision Aristocrat was already leaning toward.
What It Actually Signals for the Supplier Market
The failed deal left Playtech independent, which has consequences for the competitive landscape. An Aristocrat-owned Playtech would have created a supplier with both physical and digital dominance, potentially reshaping exclusivity deals and platform contracts across regulated markets. That didn’t happen. Playtech remains a standalone supplier competing against Evolution for live dealer market share and against Pragmatic Play and Light & Wonder for lobby presence.
For the broader industry, the collapse reinforced a pattern. Large land-based companies talk about digital transformation, but when the price of entry becomes a multi-billion-dollar acquisition with regulatory complexity across a dozen jurisdictions, the appetite fades. IGT’s merger with Everi followed a different path, focusing on land-based consolidation rather than online expansion. The message from the market is consistent: building online capability organically is slow but controllable. Buying it is fast but expensive and unpredictable.
The supplier market that feeds Canadian lobbies remains fragmented as a result. Evolution dominates live dealer. Pragmatic Play pushes volume across slots and live. Light & Wonder consolidates legacy brands. Playtech competes across all three verticals without owning any of them outright. That fragmentation is actually good for operators and, by extension, for players. It keeps licensing fees competitive and game variety broad.
What Changes for Canadian Players
Directly, nothing changes right now. The games in your lobby today will be there tomorrow. Playtech’s Age of the Gods series, its live dealer tables, its backend platform technology, all continue operating under the same contracts and the same terms. No games disappear. No operator switches platforms overnight because a takeover bid failed.
Indirectly, the failed deal preserves the current competitive dynamic. Had Aristocrat acquired Playtech, there was a real possibility of exclusivity shifts, where certain Playtech games or live dealer products could have been funnelled toward Aristocrat-partnered operators. That consolidation risk is off the table for now. Canadian players continue to benefit from a supplier market where no single company controls enough of the stack to dictate terms unilaterally.
The one thing worth watching is Playtech’s next move. An independent Playtech under shareholder pressure to demonstrate value will likely invest more aggressively in product development and market expansion. If that investment targets the Canadian regulated market, particularly Ontario’s iGaming framework, players could see more Playtech titles and better live dealer coverage in provincially regulated lobbies over the next 12 to 18 months.
Honest Assessment
The Aristocrat-Playtech deal was the clearest test case for whether a land-based giant could buy its way to online dominance, and the answer was no. Not because the strategy was wrong, but because the price of bridging two fundamentally different business models exceeded what the acquirer was willing to absorb when complications mounted. That’s a meaningful signal. It suggests the online casino supply chain will remain fragmented for the foreseeable future, which keeps competition alive and prevents any single supplier from gaining the leverage to squeeze operators or reduce player choice. For Canadian players, a competitive supplier market is a better outcome than a consolidated one, even if you never see the mechanics behind it.
The biggest deals in gambling aren’t always the ones that close. Sometimes the ones that fall apart tell you more about where the industry actually stands than a completed acquisition ever could. Aristocrat’s retreat from Playtech didn’t just preserve the status quo. It confirmed that the online casino supply chain has its own gravity, and buying your way past it costs more than even $3.9 billion can guarantee.
Gambling is entertainment with a cost attached, so set limits before you play and visit our Responsible Gaming page for support resources, safer-play tools, and help options if gambling stops feeling fun.
Leave a Comment