Your Casino Deposit Was Instant. Here’s Why the Withdrawal Takes Five Days.
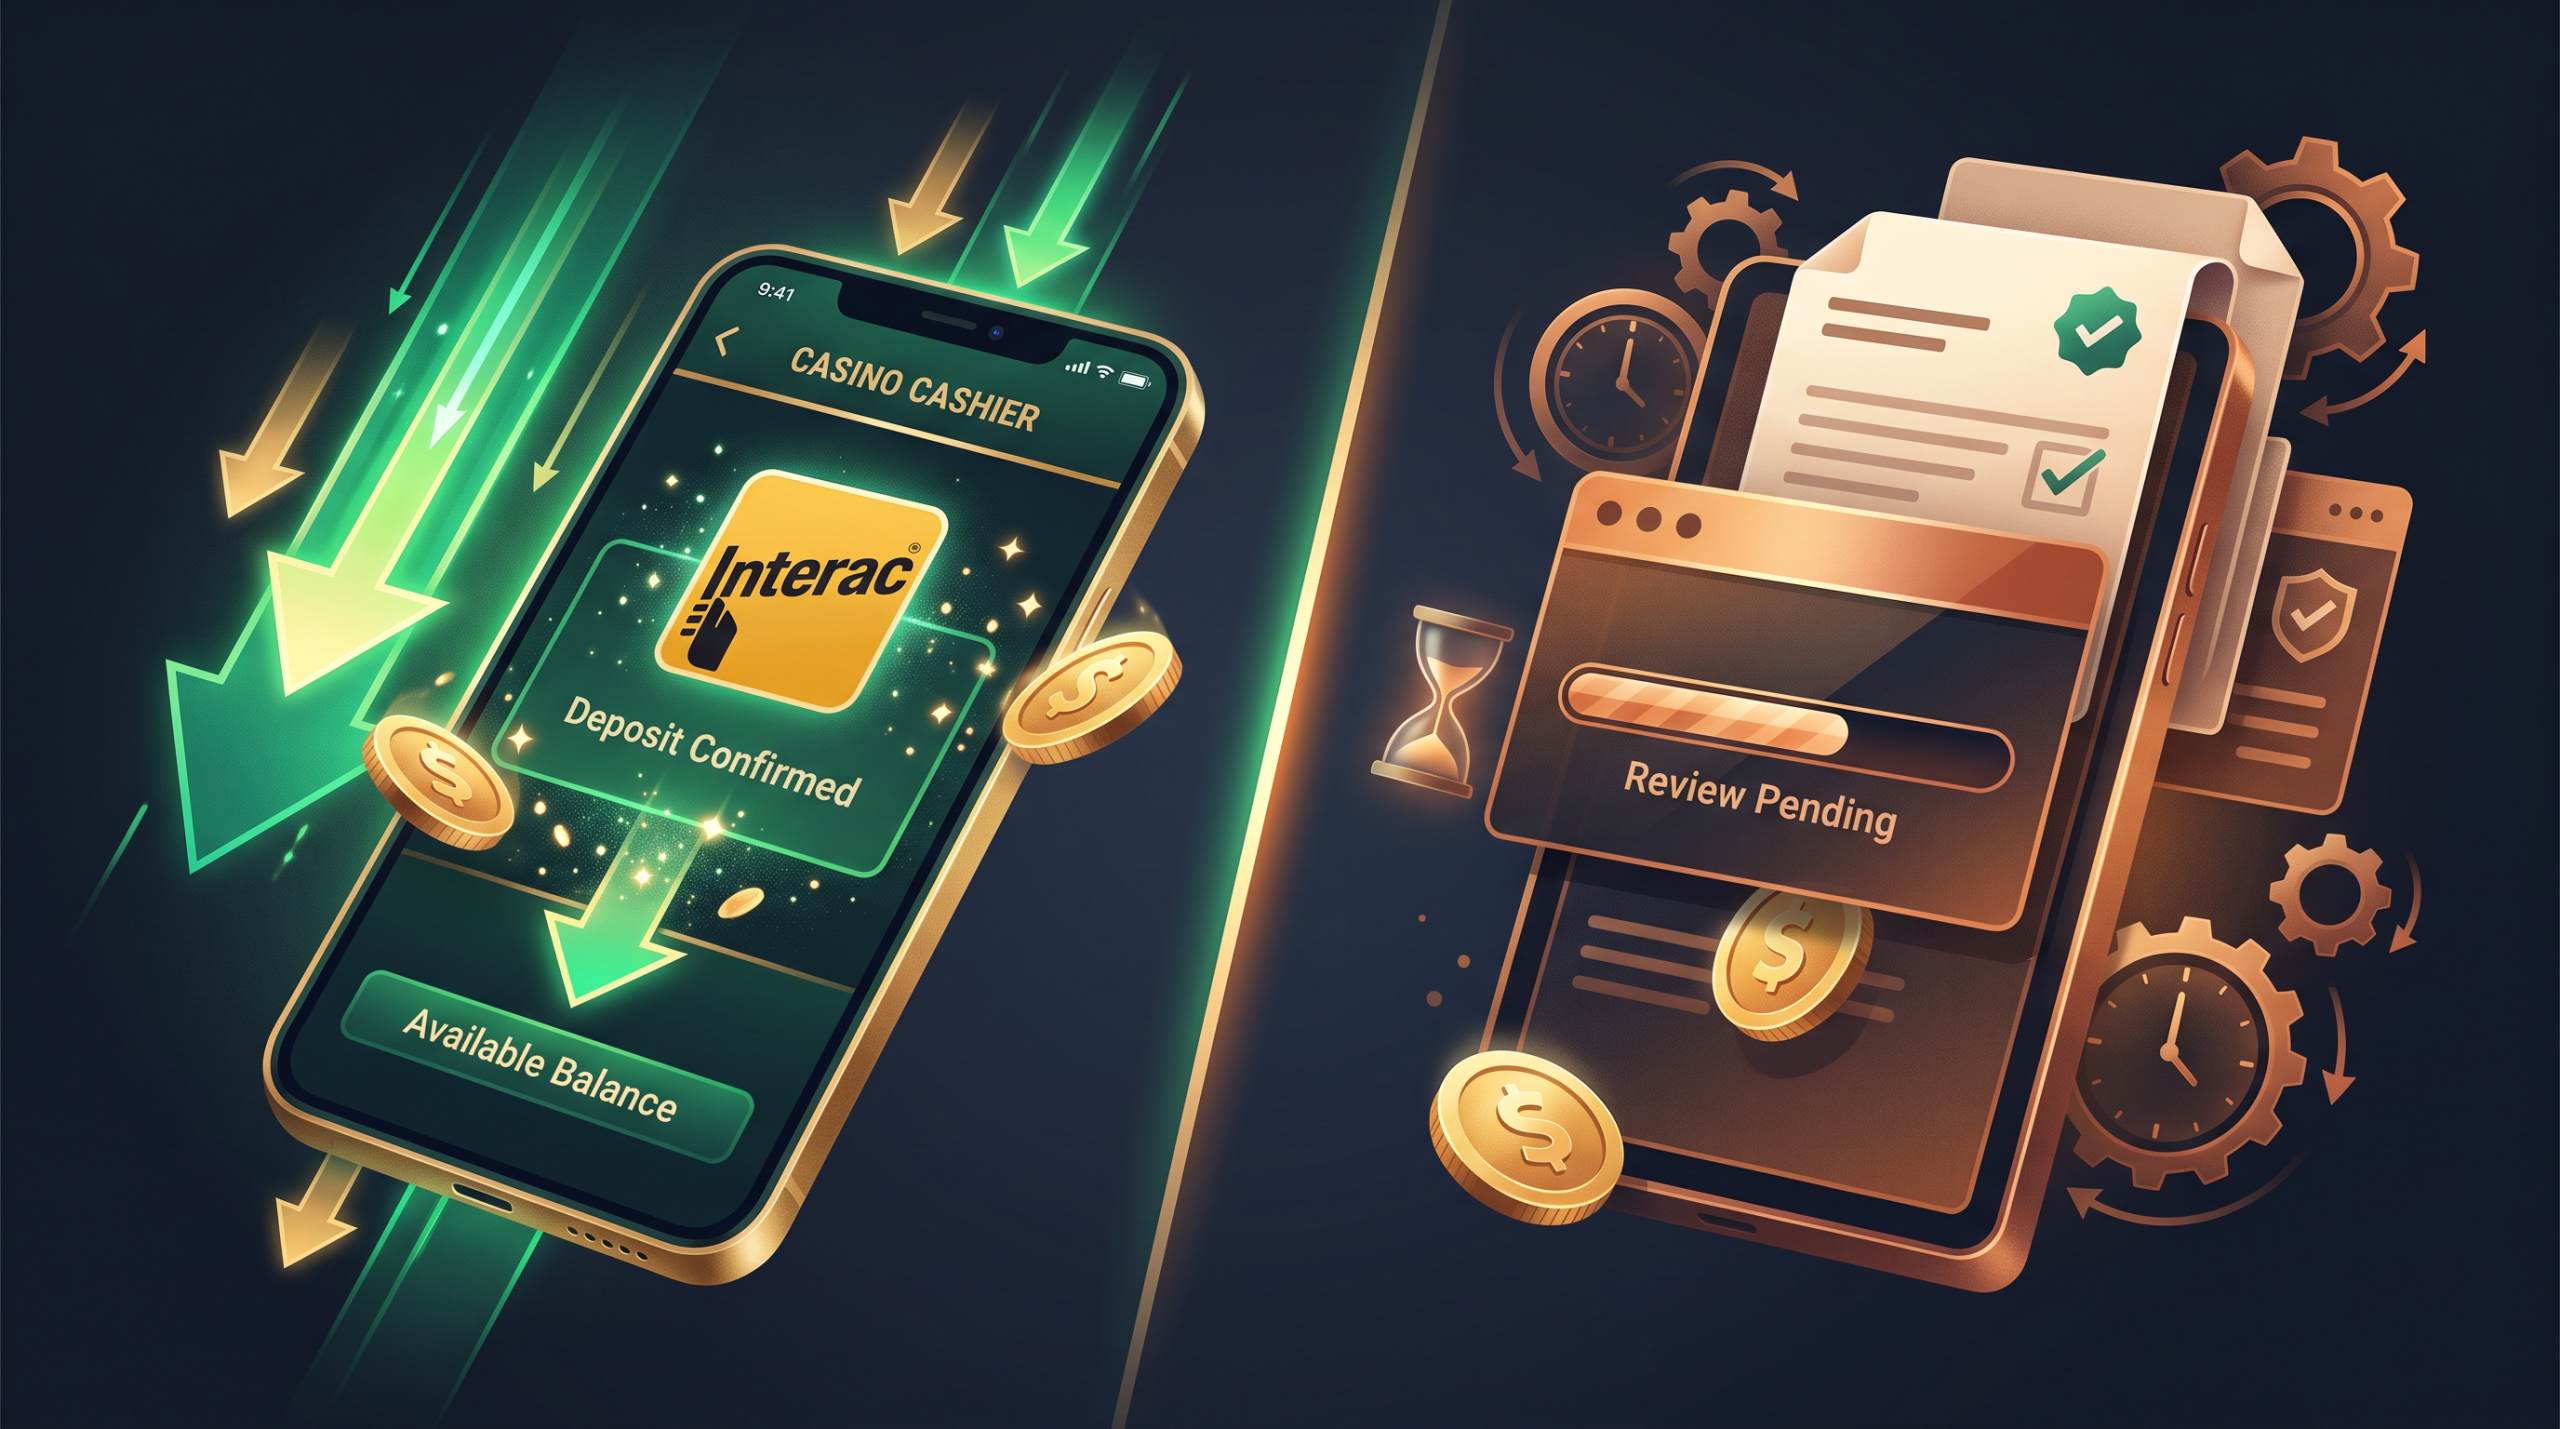
You tap “deposit,” and the money appears in your casino balance before you’ve put your phone down. You tap “withdraw,” and the same platform that processed your deposit in three seconds now needs three to five business days to send it back. The asymmetry feels wrong. It feels like the casino wants your money fast and gives it back slow on purpose. That instinct isn’t entirely misplaced, but it’s also not the full picture.
The deposit side and the withdrawal side of a casino cashier are genuinely different systems with different requirements. Some of the delay is regulatory. Some of it is operational. And some of it is a design choice that benefits the operator more than it benefits you. Knowing which is which changes how you evaluate a casino’s cashier, and it changes what you should tolerate.
Here’s what’s actually happening on each side of that transaction, and where the legitimate process ends and the stalling begins.
Why Deposits Are Instant (and It’s Not Generosity)
A casino deposit through Interac e-Transfer or a debit card is a push transaction. You’re sending money to the operator. The payment processor confirms the funds are available, the operator receives confirmation, and your balance updates. The casino’s risk in this moment is essentially zero. You’ve already authorised the payment. The money is moving toward them. There’s no reason to slow it down.
This is why deposits are instant across almost every Canadian-facing operator, whether provincially regulated or grey market. The infrastructure exists to move money in seconds. Interac e-Transfer settles quickly. Visa and Mastercard debit authorisations are near-instant. The technology isn’t the bottleneck on either side of the cashier. The difference is what happens after the money moves.
Operators also have a commercial incentive to make deposits frictionless. Every second between “I want to play” and “I’m playing” is a second where you might change your mind. The deposit flow is engineered to be fast because speed serves the business. That’s not sinister. It’s just worth noticing that the same urgency doesn’t apply going the other direction.
The Two-Stage Withdrawal Nobody Explains Clearly
When you request a withdrawal, two completely separate processes begin, and most players think of them as one. Stage one is the casino’s internal review. Stage two is the actual payment transfer. The total time you experience is both stages combined, but only one of them is visible to you.
The internal review is where the operator verifies your identity (if they haven’t already), checks whether any bonus terms are still active on your account, confirms the withdrawal method matches their policies, and runs whatever anti-fraud or anti-money-laundering checks their licence requires. This stage is entirely within the casino’s control. It can take 24 hours. It can take 72. Some operators process it in under an hour. The variance here is where the real difference between a good cashier and a bad one shows up.
Stage two, the actual transfer, is predictable. Interac e-Transfer withdrawals, once approved, typically arrive within a few hours. Bank wire transfers take two to five business days. The payment method’s speed is well-documented and consistent. If your withdrawal is taking five days and the payment method normally settles in hours, the delay isn’t the payment rail. It’s stage one.
KYC Is Legitimate. The Timing of It Is the Problem.
Know Your Customer verification is a real regulatory requirement. Operators need to confirm your identity before releasing funds. Under Ontario’s regulatory framework, this isn’t optional. Grey market operators have their own licensing requirements from jurisdictions like Malta or Curaçao that include similar obligations. The process itself, sending ID, proof of address, sometimes a selfie, is standard.
The issue is when it happens. Most operators don’t trigger KYC at deposit. They trigger it at your first withdrawal. That means the verification delay hits you at the exact moment you’re trying to take money out, not when you were putting money in. If you deposited $50 and played for a week before requesting a withdrawal, you’re now waiting for document review on top of the withdrawal processing time.
The fix is straightforward: complete KYC before you ever request a withdrawal. Most operators allow you to upload documents through your account settings at any time. Doing it on day one, before you’ve won anything, removes the single largest source of withdrawal delay. I’ve seen this cut first-withdrawal times from five days to under 24 hours at some operators.
The Pending Period Is a Design Choice, Not a Requirement
Many operators impose a “pending period” on withdrawals. This is a window, typically 24 to 72 hours, during which your withdrawal request sits in a queue before processing begins. During this window, some operators allow you to reverse the withdrawal and put the money back into your playable balance. That reversal option is not an accident. It’s a retention mechanism.
The pending period is distinct from the internal review. It’s time added before the review even starts. A casino with a 48-hour pending period followed by a 24-hour review followed by an Interac transfer is looking at a minimum of three days before you see your money, even if every step goes smoothly. A casino with no pending period and fast internal processing can get Interac withdrawals to you the same day.
Provincially regulated operators in Ontario have generally moved toward shorter or eliminated pending periods. Grey market operators vary widely. When you’re evaluating a casino’s cashier, the pending period length tells you something about how the operator views your money once you’ve decided to take it back. A 72-hour reversible pending period is the operator betting that a percentage of players will cancel the withdrawal and keep playing. The data says they’re right.
Interac for Deposits but Not Withdrawals Is a Red Flag
This pattern shows up more often than it should. You deposit via Interac e-Transfer because it’s fast, familiar, and Canadian. You go to withdraw and Interac isn’t listed. Your options are bank wire (two to five business days, sometimes with a fee) or an e-wallet you didn’t use for the deposit.
The absence of Interac for withdrawals when it’s available for deposits is worth paying attention to. It means the operator has integrated Interac’s deposit rails but hasn’t set up, or chosen to set up, the withdrawal side. Since Interac withdrawals are among the fastest options for Canadian players, the omission pushes you toward slower methods. Whether that’s a technical limitation or a deliberate choice, the effect on you is the same.
Before you deposit at any operator, check the withdrawal methods page. Not the deposit page. The deposit page will always look generous. The withdrawal page tells you what the cashier actually looks like when the money is moving in your direction.
What a Good Withdrawal Process Actually Looks Like
A well-run cashier has a few identifiable characteristics. KYC is prompted at registration or first deposit, not first withdrawal. The pending period is either absent or under 24 hours with no reversal option. Internal review is completed within 24 hours for verified accounts. And the withdrawal methods mirror the deposit methods, so if you deposited via Interac, you withdraw via Interac.
At operators meeting that standard, a Canadian player with a verified account requesting an Interac withdrawal can realistically see funds within 24 hours. That’s the benchmark. Not because every operator hits it, but because the infrastructure exists to make it possible. When an operator takes four or five days on a routine withdrawal to a verified account, the delay is a choice, not a constraint.
Some operators publish their average withdrawal processing times. When they do, check whether the figure includes the pending period or starts after it. A “24-hour processing time” that begins after a 48-hour pending period is a 72-hour withdrawal dressed up as a fast one.
Honest Assessment
The deposit-withdrawal speed gap is partly structural and partly engineered. The structural part, KYC checks, anti-fraud review, payment method settlement times, is legitimate and unavoidable. The engineered part, extended pending periods, reversal windows, missing withdrawal methods, is the operator tilting the experience in their favour. Both exist at the same time, and the ratio between them tells you a lot about how a casino treats its players.
The single most effective thing you can do is complete KYC verification the day you open your account, before you’ve played a single spin. The second most effective thing is choosing operators where Interac e-Transfer is available for both deposits and withdrawals. Those two steps eliminate the majority of withdrawal friction that Canadian players actually experience. Everything else, the pending period, the review speed, the payment method parity, is information you should check before you deposit, not discover when you’re trying to cash out.
The speed of your deposit tells you what the technology can do. The speed of your withdrawal tells you what the operator chooses to do. Those are different things, and treating them as the same is how the delay catches you off guard.
Gambling is entertainment with a cost attached, so set limits before you play and visit our Responsible Gaming page for support resources, safer-play tools, and help options if gambling stops feeling fun.
Leave a Comment