Interac e-Transfer Is the Default. Here’s What Happens When Your Casino Doesn’t Offer It for Withdrawals.
Every Canadian casino site that matters accepts Interac e-Transfer for deposits. It’s instant, it’s familiar, and it’s the way most players in this country move money online. So when you finish a session, clear your wagering, and open the cashier to pull your balance out, you’d expect Interac to be sitting right there waiting for you. Often, it isn’t. The deposit method that got you in within seconds isn’t available on the way out.
This isn’t a technical failure. It’s a structural choice that operators make based on cost, processing agreements, and how their payment infrastructure is configured. But the result for you is the same every time: a withdrawal that could have landed in your bank account in hours instead takes three to five business days through an alternative method you didn’t plan on using.
The cashier page is designed to make depositing feel frictionless. What happens on the other side of that page is where the operator’s priorities become visible.
Why Interac Deposits Are Universal and Interac Withdrawals Aren’t
Interac e-Transfer deposits work through a redirect. You click the deposit button, get sent to your bank’s login, authorise the transfer, and the funds hit your casino balance within seconds. The operator receives the money through a payment processor that handles the Interac integration. It’s a pull transaction from the player’s side, and it’s cheap and reliable for the operator to offer.
Withdrawals via Interac work differently. The operator has to push funds back to you, which requires a different processing agreement, different compliance checks, and typically a higher per-transaction cost. Not every payment processor that handles Interac deposits also supports Interac payouts. Some operators use one provider for deposits and a completely separate one for withdrawals, and the withdrawal provider may not have Interac in its stack at all.
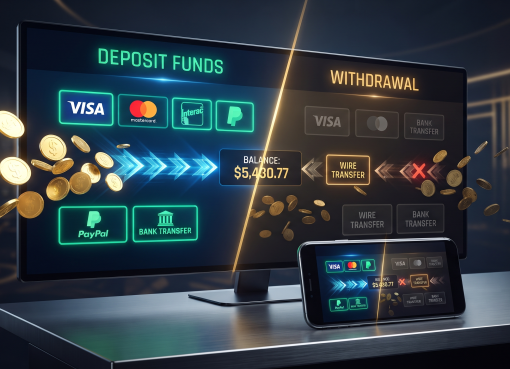
The result is that an operator can advertise “Interac e-Transfer” on its payments page and technically be telling the truth, even though it only applies to deposits. I’ve seen this pattern across dozens of Canadian-facing sites. The deposit page lists Interac prominently. The withdrawal page quietly offers bank wire, Visa Direct, or an e-wallet you’ve never used.
What You Get Instead and What It Costs You in Time
When Interac isn’t available for withdrawals, the alternatives typically fall into three categories. Bank wire transfers take three to seven business days and sometimes carry a fee of $25 to $50 CAD, depending on the operator and your bank. Visa Direct or Mastercard payouts can process in one to three business days but aren’t universally supported by Canadian banks, so there’s no guarantee the funds actually land on your card. E-wallets like MuchBetter or iDebit add a middleman step where you withdraw to the wallet and then transfer to your bank, which adds another one to two business days on top of the casino’s processing time.
Compare that to an Interac e-Transfer withdrawal at operators that do support it: once the casino approves the payout, the transfer typically arrives within two to four hours. Some operators process it in under an hour. The difference between a same-day Interac payout and a five-day bank wire isn’t marginal. It’s the difference between seeing your money before dinner and seeing it next week.
The Cashier Page Tells You Everything Before You Deposit
This is the check most players skip. Before you deposit at any Canadian casino, open the cashier page or the payments section and look specifically at the withdrawal methods. Not the deposit methods. Not the general “banking” overview that lists every logo the operator can display. The withdrawal tab. If Interac e-Transfer isn’t listed there, it won’t magically appear when you’re ready to cash out.
Some operators bury this information. The deposit page is front and centre, designed to get you funded and playing. The withdrawal page may require you to create an account first, or it may only be visible once you’ve already deposited. This is worth investigating before you commit any money. A quick check of the operator’s FAQ or terms page for “withdrawal methods” usually reveals the list, and if it doesn’t, that silence is information too.
Provincially regulated operators in Ontario tend to be more transparent about this because iGaming Ontario’s framework requires clearer payment disclosures. Grey market sites have no such obligation, and the gap between what’s advertised on the deposit side and what’s available on the withdrawal side tends to be wider.
The Pending Period Makes It Worse
Every withdrawal goes through two stages. The first is the casino’s internal review, where your payout request sits in a pending state while the operator verifies it. This can take anywhere from zero to 72 hours depending on the site, and during this window many operators allow you to reverse the withdrawal and keep playing. The second stage is the actual payment transfer, where the money moves from the operator to your account.
When Interac is your withdrawal method, the second stage is fast enough that the total wait still feels reasonable. A 24-hour pending period plus a two-hour Interac transfer means you’re looking at roughly a day. But when the withdrawal method is a bank wire with a three-to-five-day transfer time, that same 24-hour pending period means you’re now looking at four to six business days minimum. And if the operator’s internal review takes 48 to 72 hours, you could be waiting over a week for money that’s already been approved.
The pending period is the operator’s variable. The transfer time is the payment method’s variable. When both are slow, they compound in a way that makes the withdrawal experience feel deliberately obstructive, even when each individual step is technically within the stated timeframe.
Why Some Operators Choose Not to Offer It
There’s a cost calculation behind this decision. Interac e-Transfer withdrawals cost the operator more per transaction than bank wires in many processing arrangements. For a high-volume operator processing thousands of payouts per day, the difference between a $1.50 Interac payout fee and a $0.50 batch wire fee adds up quickly. Some operators absorb the cost because fast withdrawals are a competitive advantage. Others decide the savings justify pushing players toward slower methods.
There’s also a behavioural angle that’s harder to prove but difficult to ignore. Slower withdrawals mean longer pending periods, and longer pending periods mean more opportunities for players to reverse their payouts and continue playing. I’ve seen enough cashier page designs to recognise when the “reverse withdrawal” button is more prominent than the “confirm” button. An operator that genuinely wants you to receive your money quickly has no reason to make the fastest withdrawal method unavailable while keeping the slowest ones front and centre.
Transfer Limits Are Your Bank’s Decision, Not Interac’s
One detail that catches players off guard: even when Interac e-Transfer is available for withdrawals, the amount you can receive in a single transfer is limited by your bank, not by Interac itself. Most major Canadian banks cap incoming e-Transfers at $3,000 to $10,000 CAD per transaction, and some set daily or weekly limits that are lower than the casino’s stated maximum withdrawal. TD, RBC, BMO, and Scotiabank all publish their Interac limits, and they vary.
If you’re withdrawing $5,000 CAD and your bank’s incoming e-Transfer limit is $3,000, the casino may split it into two transfers or default to a different method entirely. This isn’t something the operator always warns you about in advance. Checking your bank’s Interac limits before requesting a large withdrawal saves you from a surprise redirect to a slower payment channel.
Honest Assessment
The absence of Interac e-Transfer for withdrawals is one of the clearest signals of where an operator’s priorities sit. It doesn’t automatically make a casino bad. Some otherwise solid platforms use bank wires or Visa Direct for payouts and process them promptly. But when an operator accepts Interac deposits instantly and then routes your withdrawals through a five-day bank wire, the asymmetry is a deliberate business choice, and it’s one that consistently benefits the operator more than the player.
If fast access to your money matters to you, and it should, check the withdrawal methods before you deposit. Treat the cashier page as a two-way street. If Interac is only available in one direction, factor that delay into your decision. There are enough Canadian-facing operators that offer Interac withdrawals that you don’t have to settle for a site that only uses it to take your money in.
The deposit experience is the pitch. The withdrawal experience is the product.
Gambling is entertainment with a cost attached, so set limits before you play and visit our Responsible Gaming page for support resources, safer-play tools, and help options if gambling stops feeling fun.
Leave a Comment